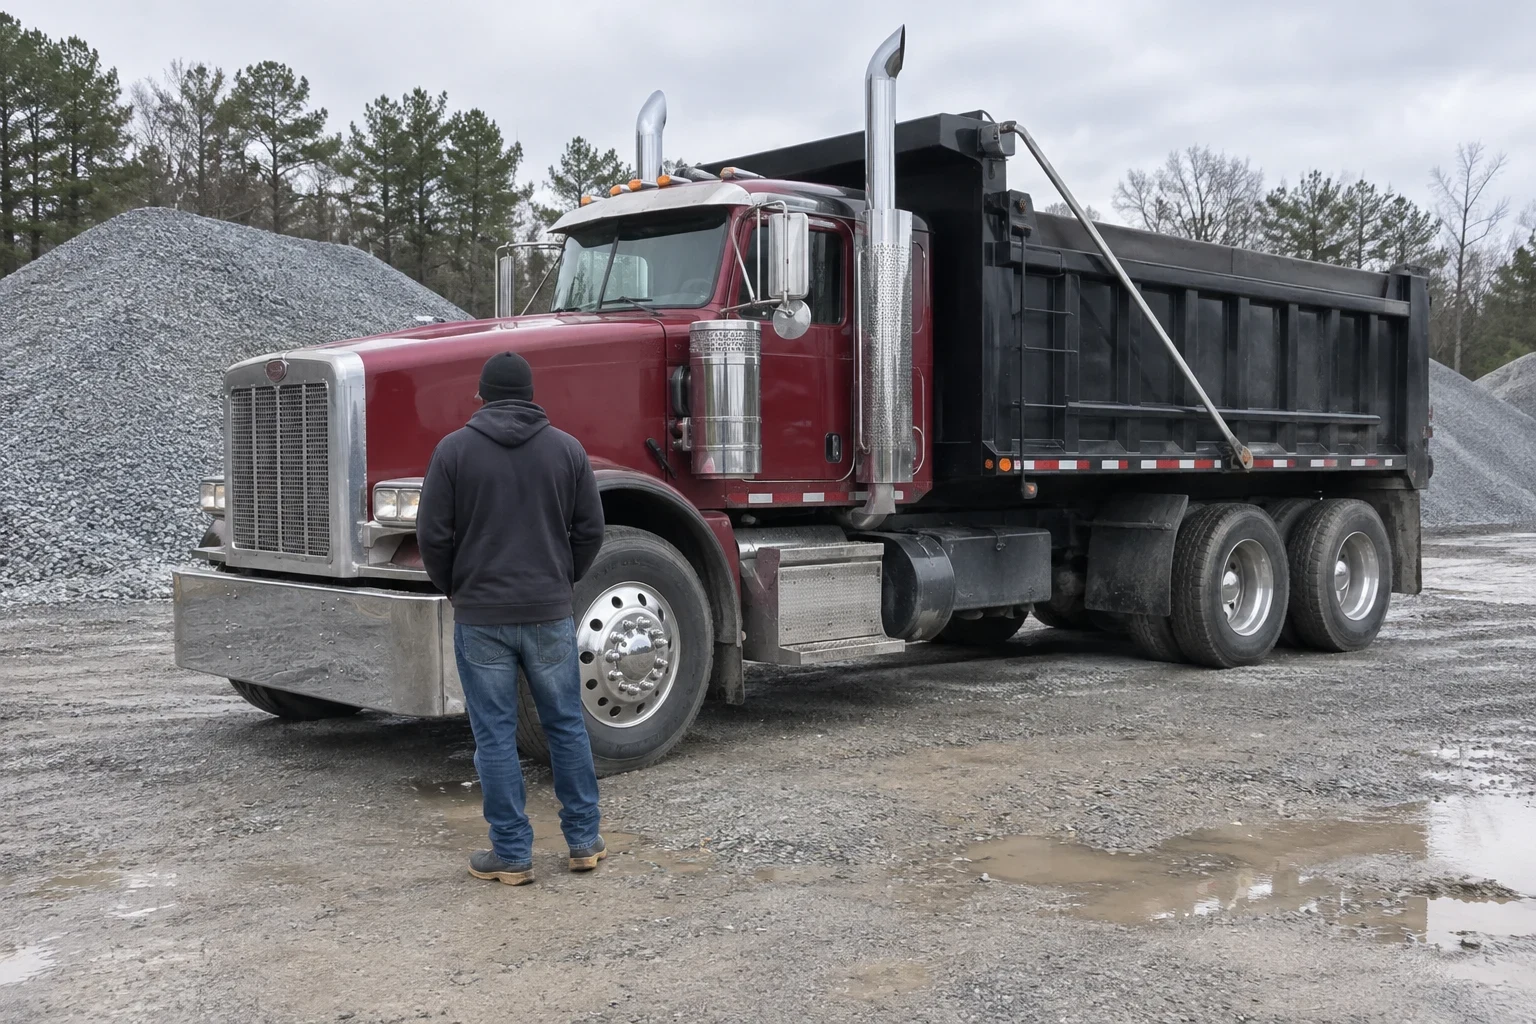
ServicesDump Truck Insurance
Dump Truck and Construction Truck Insurance in Decatur
We set up coverage for dump trucks, roll-offs and construction trucks based on how you actually work: what you haul, how far you run and which contractors need your paperwork. After your policy starts, we check back so nothing slips before the next job.
Coverage built for loads, job sites and tipping beds
A dump truck does not work like a long-haul tractor. It runs short trips, makes many stops, backs onto unfinished ground and raises a loaded bed several times a day. Underwriters price that risk differently, and a policy written for a highway rig can leave gaps on a job site.
We start with the details of your operation: the trucks, the drivers, the materials and the radius. Then we explain each coverage in plain words so you know what pays when a truck rolls on a soft shoulder or a load of gravel cracks a windshield on the road behind you.
Once you are covered, we stay in touch. We check in after the policy begins, help you add or drop trucks, and remind you what to keep current so renewal is not a scramble.
What goes into a dump truck policy
Primary auto liability
When your truck is at fault in a crash, this coverage handles injuries and damage to other people and their property. Regulators and contractors check it before anything else, and the limit you hold can decide which jobs are open to you.
Physical damage for the truck and body
Collision and comprehensive cover the chassis along with the dump body. We list the body and any extra equipment separately so the stated value matches a real replacement cost.
Cargo coverage, when it fits
Loads of dirt and fill seldom call for it, though certain materials and contracts do. We give you a straight answer on whether motor truck cargo insurance is worth it for what you haul.
Certificates of insurance
Many general contractors and municipalities want a certificate with their name on it before your truck enters the site. We prepare those for you and keep a record of every party that has requested one.
Filings and DOT details
When your operation requires state or federal filings connected to your DOT number, we line up the policy and the filings so they agree.
Signs it is time to review your coverage
A contractor rejected your certificate
When a general contractor wants higher limits or particular wording, your current policy may fall short. Caught before the job begins, it is usually an easy adjustment.
You bought another truck
Any new truck or dump body has to be added at the right value. Putting it to work uninsured, even for a few days, is a serious exposure.
Your hauling radius changed
Taking jobs farther from the yard, or crossing into another state, can shift your rating and the filings you are required to carry.
Renewal came back much higher
A big premium increase almost always traces back to something specific. It might be a recent loss, an added driver or carriers tightening up across the market. We track down the cause and look at what else is available.
You hired a driver with a spotty record
Carriers pull a motor vehicle record for every driver. Putting someone behind the wheel without letting us know can create problems when a claim comes in.
How we set up your policy
- 1
Talking through your work
You can sit down with us at our office or connect by phone or video, whatever suits your schedule. We want to hear about your loads, your routes, your drivers and the contractors who hire you.
- 2
Gathering the details
Keep your DOT number, truck VINs, values, driver list and any prior loss runs close by. Gaps in that information hold up the quote, so we give you a clear list of anything still missing.
- 3
Options explained side by side
We compare limits, deductibles and the exclusions in each option. You make the call with the full picture in front of you, not a pitch.
- 4
Binding, filings and certificates
After you choose, we bind the coverage, take care of the filings and send out the certificates your contractors are waiting on.
- 5
Checking back after you start
A few weeks after the start date, we follow up to confirm contractors accepted your certificates and every truck is listed correctly. Ahead of renewal, we go over what has changed in your operation so the next policy still fits.
What moves the price of dump truck coverage
Every quote depends on your trucks and how you run them. We explain which factors carry the most weight for your operation so the number makes sense before you sign.
- What you haul
- Sand and fill rate differently from asphalt, demolition debris or heavy aggregate. The material affects both liability and cargo pricing.
- Radius of operation
- Trucks that stay close to the yard usually cost less to insure than trucks running long distances.
- Drivers and loss history
- Clean records and a quiet claims history help the most. Newer operations with no track record often pay more at first.
- Truck value and limits
- Higher stated values and higher liability limits raise the premium. Deductible choices can balance that out.
Questions about dump truck and construction truck insurance
Something not covered here? (404) 620-4683
Am I covered if the truck tips over while the bed is raised?
It comes down to the physical damage coverage on your policy. An upset is usually handled under collision, but carriers word it differently. We go over that section with you so you know the answer before a soft spot on a job site tests it.
Do I need a DOT number if I only haul inside Georgia?
Often you do, depending on the truck's weight and the kind of work you take on. Intrastate and interstate hauling follow different rules. We review your setup and tell you which filings apply to you.
Can you add a contractor to my certificate for a single job?
Yes. With an active policy, we can issue a certificate naming any contractor who asks for one. Send us the exact wording they want, and we compare it to your policy before it goes out.
I am leased to a hauling company. What do I need?
When you run under their dispatch, the company you are leased to frequently provides the primary liability. Your own truck damage and the time you drive off dispatch are a separate matter, which is where physical damage and non-trucking liability (bobtail) insurance come in. We read both sides and show you exactly where their protection stops and yours has to start.
What happens after my policy starts?
We reach back out to make sure your certificates and truck listings are working the way they should. If you plan to add equipment or a driver, give us a call first so the change is on the policy before that truck heads to a site.
Get your dump trucks covered right
Tell us about your trucks, your loads and your contractors. We will walk you through options and keep in touch once your coverage is in place.